Behavioral health clinic liability insurance for owners protects personal wealth by covering business risks that standard malpractice policies do not address, such as premises liability or employment-related lawsuits. These specialized policies ensure that clinic owners are financially shielded from legal defense costs and settlement fees that could otherwise threaten their individual assets.
Running a high growth behavioral health clinic in Texas demands more than clinical excellence; it requires a sophisticated approach to enterprise risk that simple malpractice policies cannot provide. Many owners mistakenly believe their professional liability coverage shields their personal wealth from the multifaceted threats inherent in operating Intensive Outpatient Programs or Psychosocial Rehabilitation centers. However, a single employment dispute or a regulatory oversight can bypass standard protections, placing your private assets at immediate risk. This guide moves beyond basic coverage to examine the architecture of comprehensive liability insurance. We will analyze the evolution from practitioner insurance to enterprise risk strategy, the critical role of Employment Practices Liability Insurance, and the nuances of Sexual Abuse and Molestation coverage. You will learn how to align your insurance portfolio with a long term wealth design strategy to ensure your legacy remains secure in an increasingly litigious landscape.
The Evolution from Practitioner Insurance to Enterprise Risk Architecture
Early in a clinician's career, professional liability insurance is often viewed as a commodity. A solo therapist might pay as little as $150 to $500 annually for a basic policy that satisfies licensing boards and provides a baseline level of peace of mind. However, for the owner of a $1M to $10M behavioral health clinic, this practitioner level mindset is a dangerous liability. As a business scales into Intensive Outpatient Programs (IOP) or Psychosocial Rehabilitation (PSR), the complexity of operations introduces systemic risks that an individual malpractice policy was never designed to handle.
At this stage, insurance must evolve from a regulatory checkbox into a comprehensive Risk Architecture. We define Risk Architecture as a layered, strategic approach to coverage designed specifically to protect the owner’s private balance sheet. In a high revenue clinic, the surface area for litigation expands far beyond clinical judgment to include employee misconduct, facility accidents, and complex data breaches. If the insurance structure is not robust, these liabilities can easily pierce the corporate veil, placing the owner’s personal real estate, investment accounts, and their Wealth Design strategy at risk.
Effective Risk Architecture serves as the first line of defense in Asset Protection for Behavioral Health Clinic Owners. While startup guides often list insurance as a single line item alongside rent and utilities, enterprise owners must treat behavioral health clinic liability insurance for owners as a critical component of their specialized financial architecture services. It is the defensive wall that ensures clinical errors do not become personal financial catastrophes. By shifting from reactive coverage to intentional risk engineering, owners can focus on clinical excellence while knowing their personal wealth is insulated from practice level risks.
Why Standard Malpractice Coverage is Insufficient for PSR and IOP Operators
Standard malpractice policies are designed to protect the individual clinician, often focusing on clinical negligence or licensing defense. While these policies are necessary for mental health technicians and therapists, they leave the clinic owner exposed to vicarious liability. In a $1M to $10M enterprise, the owner is legally responsible for the actions, errors, and omissions of every staff member on the payroll. If a clinician in a Psychosocial Rehabilitation (PSR) program fails to document a crisis intervention correctly or if an Intensive Outpatient Program (IOP) team member engages in boundary violations, the litigation will inevitably name the facility and its ownership.
The transition to team based care in PSR and IOP settings significantly increases the surface area for risk. Unlike a solo practice, these programs involve multiple touchpoints between patients and staff, creating complex chains of responsibility. A single patient might interact with a case manager, a group facilitator, and a supervising psychiatrist in a single week. This collaborative environment, while clinically effective, creates an aggregate risk profile that a standard individual policy cannot cover. The risk is no longer confined to one room; it is distributed across the entire clinical operation.
Owners often research how much a $1,000,000 professional liability policy costs, expecting a simple premium quote based on headcount. However, for a facility, the focus must shift from per occurrence limits to aggregate limits and entity coverage. A $1,000,000 limit that satisfies a single clinician is insufficient when shared across a group of twenty employees. Without specialized behavioral health clinic liability insurance for owners, a series of small claims can quickly exhaust coverage limits, leaving the owner’s personal assets as the secondary source of settlement funds. Ensuring that insurance is integrated into specialized financial architecture services is the only way to verify that the policy actually covers the entity, not just the individuals working within it. Proper Asset Protection for Behavioral Health Clinic Owners requires recognizing that the clinic's liability is an enterprise wide threat, not a series of isolated clinical risks.
The Core Pillars of Behavioral Health Clinic Liability Insurance for Owners
Structuring a $1M to $10M enterprise requires moving beyond basic policies toward a multi-dimensional risk framework. A sound architecture for behavioral health clinic liability insurance for owners rests on four specific pillars that, when properly integrated, ensure no single event can trigger a catastrophic drain on the firm’s cash flow.
General Liability: This covers physical risks such as slip and fall incidents occurring on the premises. In the Dallas market, property managers for high quality clinical space often mandate higher limits for behavioral health tenants than for standard professional services. Owners should expect requirements for at least $2,000,000 in aggregate coverage to satisfy local lease covenants.
Professional Liability: While previous sections addressed the limitations of individual policies, the entity level pillar must provide specific defense for the clinic’s clinical protocols and treatment outcomes across all staff members. This is the primary defense against vicarious liability claims.
Cyber and HIPAA Liability: Data breaches are a primary source of financial leakage. For clinics operating PSR or IOP programs with integrated EHR systems, this coverage protects against the forensic costs, legal fees, and regulatory fines associated with a HIPAA violation.
Employee Benefits Liability (EBL): Often overlooked in specialized financial architecture services, EBL covers administrative errors in managing employee benefits, such as failing to add a new hire to the health plan or errors in 401(k) administration.
Failing to coordinate these pillars creates coverage gaps where one policy excludes a claim because it supposedly belongs under a different category. A cohesive Wealth Design strategy requires that these four areas function as a unified shield, ensuring Asset Protection for Behavioral Health Clinic Owners remains intact during litigation or regulatory audits.
Employment Practices Liability Insurance (EPLI): The Owner's Shield Against Team Risks
Managing a clinical team in high-acuity settings like PSR or IOP involves more than just oversight of patient outcomes; it requires managing human volatility in a high-stress environment. While Workers’ Compensation covers physical injuries sustained on the job, it provides zero protection against legal action stemming from administrative or interpersonal conflicts. This is where employment practice liability EPLI becomes an essential component of the clinic’s defensive posture.
EPLI specifically addresses claims involving wrongful termination, sexual harassment, discrimination, and retaliation. In a clinic generating $5M in annual revenue, the overhead and staffing levels are significant enough that a single disgruntled employee can initiate litigation that drains hundreds of thousands of dollars in legal defense fees alone. For an owner, this is not just a business expense; it is a direct leak in their Wealth Design strategy.
This specific aspect of behavioral health clinic liability insurance for owners ensures that the personal balance sheet remains insulated from the unpredictable nature of workforce management. By incorporating EPLI into specialized financial architecture services, owners transform a potential catastrophic loss into a manageable, insured business risk. This layer of Asset Protection for Behavioral Health Clinic Owners ensures that team-based risks do not compromise the owner’s long-term financial independence.
SAM Insurance: Navigating Sexual Abuse and Molestation Coverage for Clinics
For clinic owners managing high-acuity environments, Sexual Abuse and Molestation (SAM) coverage is a non-negotiable component of a robust financial architecture. Many lower-tier policies designed for small practices contain a specific abuse or molestation exclusion that removes coverage for these claims entirely. For an enterprise generating $1M to $10M, this gap represents a catastrophic vulnerability. The risk is particularly acute in PSR and IOP settings where staff members have frequent, intense contact with minors or vulnerable populations.
The financial danger of a SAM claim is not limited to potential settlements; the legal defense costs alone often exceed the total annual revenue of a smaller facility. Even false accusations require a high-level forensic defense that can cost hundreds of thousands of dollars. Without dedicated SAM coverage, these expenses act as a direct leak, pulling capital away from your Wealth Design strategy and forcing the owner to use personal assets for defense.
Integrating SAM coverage into specialized financial architecture services ensures that the policy includes both the entity and the owner as named insureds. This provides a specialized layer of Asset Protection for Behavioral Health Clinic Owners, shielding personal investment accounts from the volatility of clinical staff conduct. Proper behavioral health clinic liability insurance for owners requires verifying that this coverage is affirmative, rather than relying on the hope that it is hidden within a standard general liability policy.
The Texas Regulatory Environment: Liability Considerations in Dallas and Beyond
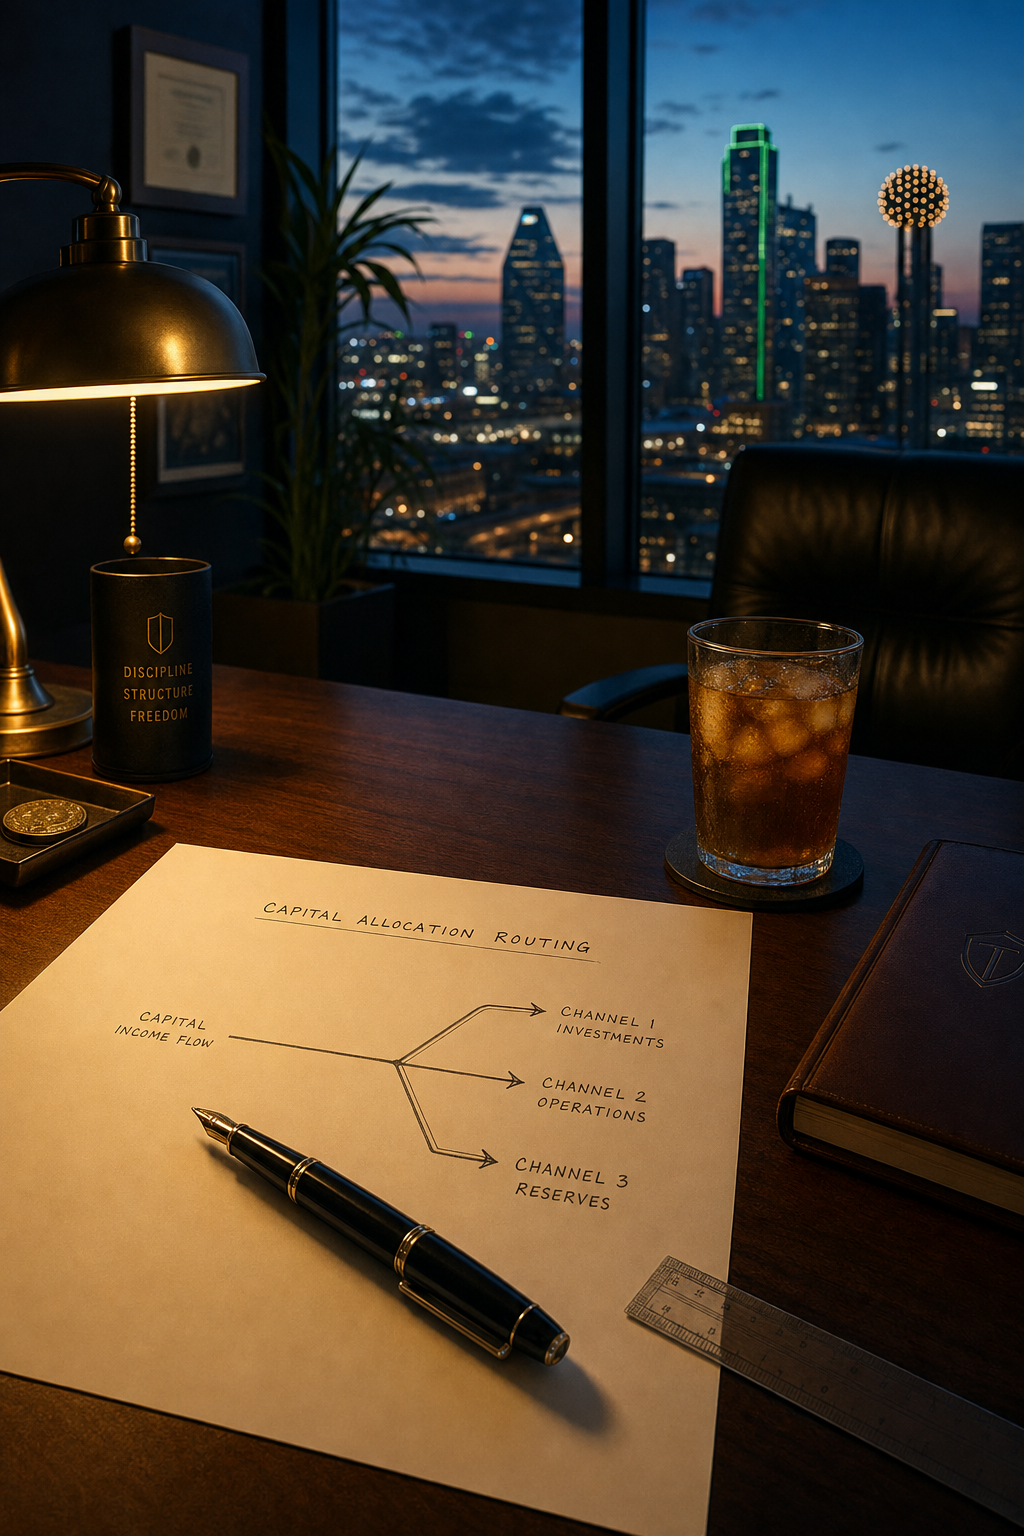
Operating in Dallas requires an understanding of the Texas Civil Practice and Remedies Code, particularly Chapter 74, which governs medical liability. While Texas is often viewed as a tort reform state, behavioral health clinic owners must navigate complex definitions regarding what constitutes a medical liability claim versus a general negligence claim. In North Texas, the litigation environment is increasingly aggressive; a generic national policy may not account for the specific ways Texas courts interpret the duty of care for PSR and IOP facilities.
Securing behavioral health clinic owner insurance liability coverage Texas requires riders that address state specific mandates, such as those overseen by the Texas Health and Human Services Commission (HHSC). These riders provide critical defense for administrative hearings and regulatory audits that can precede a civil lawsuit. For clinics generating $1M to $10M, these state level nuances are not just legal hurdles; they are potential financial leaks. Incorporating these Texas specific protections into specialized financial architecture services ensures that your insurance posture reflects the actual legal climate of the Dallas Fort Worth metroplex. This localized approach is a foundational element of Asset Protection for Behavioral Health Clinic Owners, preventing regional litigation trends from eroding the capital intended for your Wealth Design strategy. By aligning behavioral health clinic liability insurance for owners with Texas regulatory realities, the firm’s defense remains as robust as its growth.
Integrating Insurance into a Long Term Wealth Design Strategy
At the enterprise level, insurance premiums are not merely overhead expenses; they are the primary mechanism for leak prevention within your wealth pipeline. Every dollar lost to an uninsured claim, a high deductible, or an overpaid premium for redundant coverage is a dollar that fails to reach your personal balance sheet. Integrating behavioral health clinic liability insurance for owners into a broader Wealth Design strategy requires a rigorous audit of the entire risk portfolio.
We often find clinic owners paying for overlapping coverage across multiple riders while remaining dangerously underinsured for the enterprise risks mentioned in earlier sections. This inefficiency is a silent drain on cash flow. By refining these policies, we eliminate the waste and redirect that capital into specialized financial architecture services. This strategic alignment ensures that insurance serves as a foundational layer of Asset Protection for Behavioral Health Clinic Owners, protecting the capital intended for long term independence rather than just meeting a minimum regulatory requirement.
Securing your clinic goes beyond standard malpractice coverage; it requires a comprehensive approach to protect your personal wealth from unforeseen business liabilities. Balancing clinical care with complex risk management is a significant challenge for any owner. If you want expert help navigating these legal and financial safeguards, you can read more About our approach at Chia Dex Ventures LLC. Our team focuses on building sustainable foundations so you can focus on your patients with peace of mind.